Mastering the Midterms: August’s surge signals a faster, more expensive fall ahead
By
Kailee Doherty
Marketing Manager
Published
September 30, 2026
Table of contents
Welcome to Mastering the Midterms, a series dedicated to breaking down the data, trends, and shifts defining the 2026 political advertising landscape.
With the general election field set and campaigns turning their full attention to November, August marked the moment this cycle shifted from a gradual ramp into a faster, more compressed pace. And in a faster cycle, budget alone won’t win the best inventory. How quickly a campaign can secure and activate placements is becoming just as important as how much it has to spend.
This cycle’s growth is outpacing 2024’s curve. Total political CTV impressions on the Madhive platform are up 117% compared to the same point in the 2024 presidential cycle, and they jumped 260% month over month from July. With that trajectory, the fall ahead looks likely to move faster and cost more.
What August’s numbers signal for the fall
Our data lines up with the wider industry. AdImpact tracked $796.5 million in aired political ads in August, up 63% from July 2026 and 47% from August 2022. Total political spend across all channels reached $6.1 billion through August 24, up from $4.8 billion in mid-July. Streaming already accounted for $1.14 billion of that before the fall surge was underway, so its share is set to climb even faster in the weeks ahead.
AdImpact’s mid-year update raised its full-cycle forecast from $10.8 billion to $11.6 billion, CTV estimate climbing from $2.5 billion to $2.7 billion. This cycle is moving faster than most models anticipated at the start of the year, and faster cycles reward faster-moving campaigns.
Where the volume is concentrating
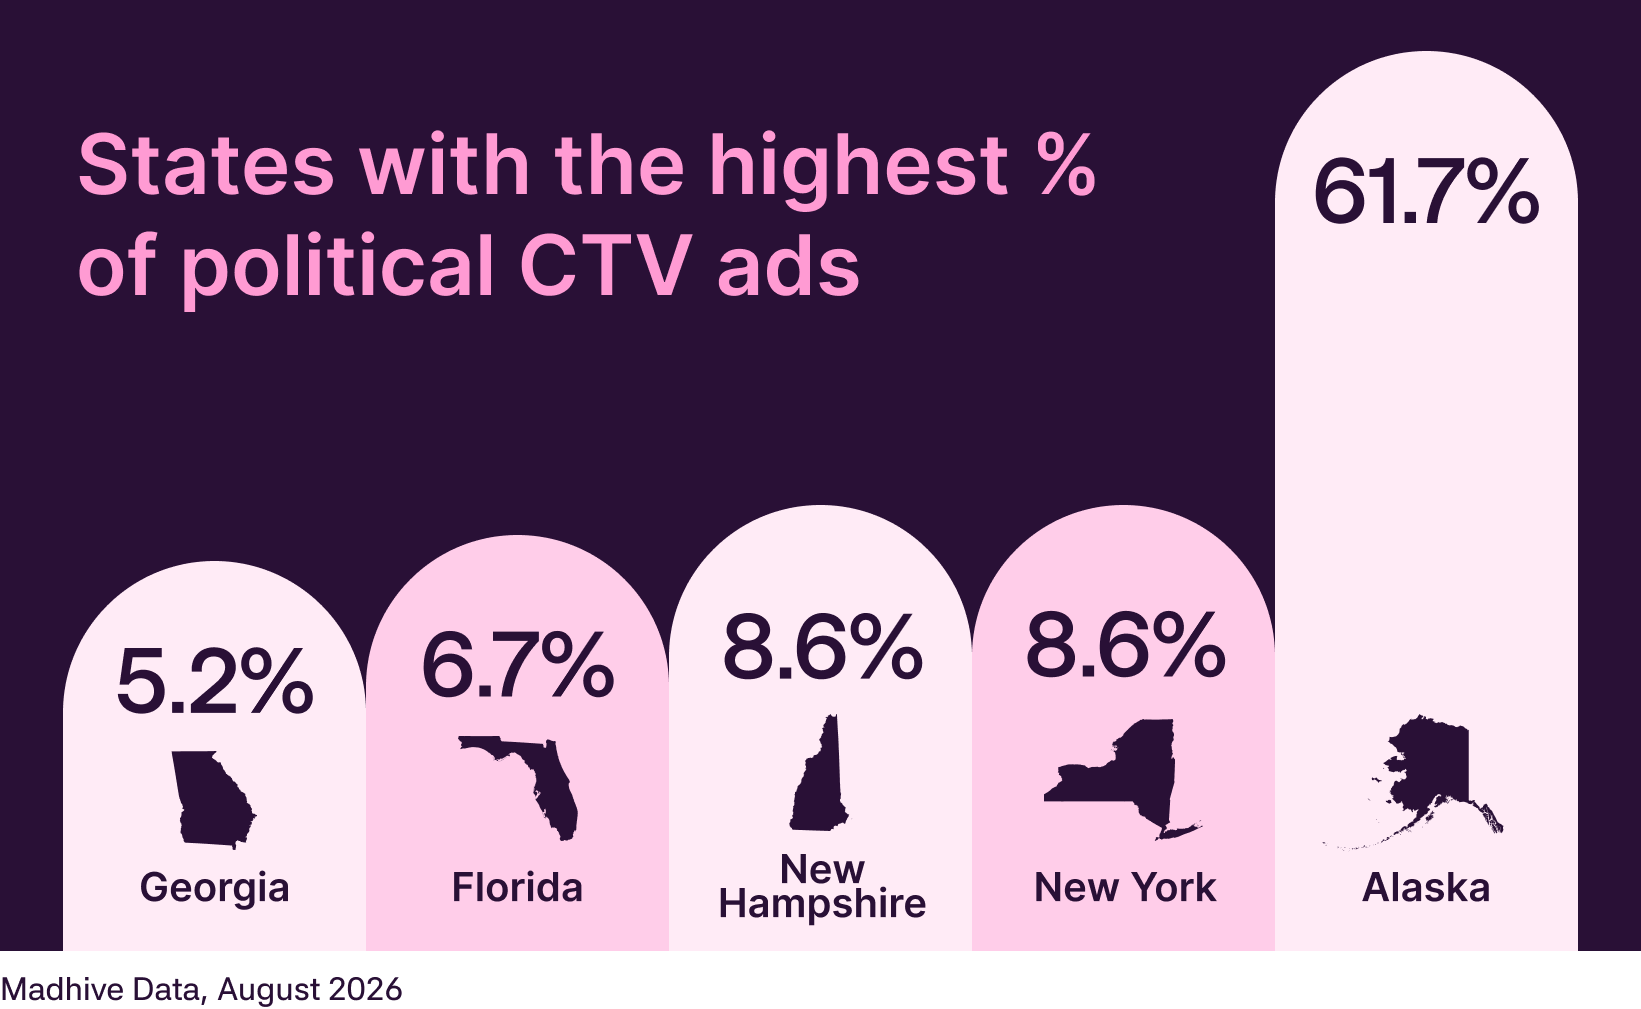
The states carrying the most political CTV volume in August – Florida, New York, Georgia, Alaska, and Arizona – aren’t surprising on their own. They’re home to some of the most competitive Senate, House, and gubernatorial races in the country, and activity in these markets has been building well ahead of the traditional October scramble.
AdImpact’s numbers show that more is still to come. The 2026 cycle has reached $5.57 billion in tracked and reserved spending, less than half of the $11.6 billion full-cycle forecast. More than half the dollars expected for the entire election season are still ahead, which means the volume yet to land could outweigh everything spent so far if August’s growth rate holds or accelerates further.
What accelerated spending means for inventory
When spending accelerates this early and this fast, two things tend to follow. Competition for premium local CTV inventory in contested markets tightens ahead of the usual pre-election crunch, and prices follow. That dynamic is the throughline of this cycle so far, and it’s consistent with what our data and the broader industry numbers show: a fall season on pace to move faster, and cost more, than 2024.
Key takeaways from August numbers
Speed is becoming as important as budget: As inventory tightens in the highest-growth markets, execution speed, meaning how quickly a campaign can secure and activate CTV placements, is emerging as a real differentiator alongside budget size. Platforms built for rapid, high-volume deployment matter more now than earlier in the cycle.
The pace has changed, not just the volume: With roughly a third of the cycle’s projected spend still to land, the months ahead are likely to bring compressed timelines and faster reservations rather than a gradual buildup. Campaigns and media partners planning around a slow fall ramp are working from an outdated timeline.
Local sellers have a narrowing window on premium rates: Broadcasters and streaming partners in contested markets are watching demand build ahead of the traditional October crunch. Locking in commitments now, before buyers start re-optimizing toward whatever inventory remains, helps protect against getting squeezed out later.
Looking ahead
Every remaining dollar is now pointed at November 3rd, and the pace set in August suggests the final stretch will be the most crowded of the cycle. Inventory in contested markets won’t sit open for long, and prices will climb as it fills. Moving early is the simplest way to stay ahead.